Financial Highlights:
- Revenue growth of 22.5% to £66.3 million (H1 2026: £54.2 million)
- Revenue per Principal up 14.5% to £133.8k (H1 2026: £116.8k)
- Adjusted PBT up 31.3% to £9.6 million (H1 2026: £7.3 million) representing an adjusted PBT margin of 14.5% (H1 2026: 13.6%)
- Adjusted basic EPS of 23.1p (H1 2026: 17.8p)
- Cash generated from operations up 19.2% to £8.1 million (H1 2026: £6.8 million) with operating cash conversion of 95.6% (H1 2026: 104.2%)
- Strong balance sheet with net cash of £10.5 million (H1 2026: £6.5 million)
- Declared interim ordinary dividend of 9.6p per share and special dividend of 15p (H1 2026: interim ordinary dividend 7.5p)
Operational Highlights:
- Ongoing operational strength underpins high-quality sustainable growth
- Maintained solid recruitment activities despite ongoing geo-political uncertainty
- 148 new applicants in the Period (H1 2026: 164)
- 23 high-calibre new Principals added bringing total Principals to 501 (31 January 2026: 491), reinforcing Keystone’s brand and market position
- Principals continue to grow their Pods with net growth of 18 other fee earners in the Period bringing total fee earners to 682 (31 January 2026: 654)
- Extended AI capabilities with rollout of CoCounsel Legal, a professional-grade generative AI tool specifically designed for the legal industry, complementing additional AI tools deployed in FY2026
- Completed brand refresh, launching new website alongside the production of extensive marketing collateral
- Central office team continues to provide service delivery excellence
Current Trading and Outlook:
- The Group has made a positive start to H2 2027
- The Board now expects that Keystone will deliver FY 2027 revenue comfortably ahead and profits materially ahead of current market expectations(1),
(1) Management understand market expectations prior to this announcement for FY2027 to be: revenue £123m, adjusted PBIT £13.8 and adjusted PBT £15.8m.
James Knight, Chief Executive Officer of Keystone, commented:
“I am extremely pleased with Keystone’s performance in the Period. Strong demand across the business, continued recruitment of high-calibre lawyers and disciplined investment in our platform have delivered excellent financial performance and further strengthened our market-leading position.
We continue to invest in our technology, brand and community, including the rollout of further market-leading AI tools, to ensure our lawyers have the infrastructure and support they need to grow and sustain successful practices. With a strong first half and an encouraging start to H2, we remain confident in Keystone’s ability to deliver sustainable long-term growth.”
Analyst Briefing
A virtual meeting for sell-side analysts will be held virtually at 9.30 a.m. on Monday, 14 September 2026. Sell-side analysts wishing to attend this event can register via email at: keystonelaw@vigoconsulting.com
Retail Investor Presentation
Keystone's management team will provide a separate presentation and Q&A for retail investors at 1.00 p.m. on Tuesday, 15 September 2026.
The presentation will be hosted on the Investor Meet Company platform, where questions can be submitted pre-event up until 9.00 a.m. on the day before the meeting, or at any time during the live presentation.
Investors can register for free and subscribe to alerts on Keystone by visiting:
www.investormeetcompany.com/keystone-law-group-plc/register-investor
Investors who already follow Keystone on the Investor Meet Company platform will automatically be invited.
The information contained within this announcement is deemed to constitute inside information as stipulated under the Market Abuse Regulation (EU) No. 596/2014 as it forms part of UK domestic law by virtue of the European Union (Withdrawal) Act 2018 (“MAR”).
Notes to editors
Keystone (AIM: KEYS) the premier tech-enabled platform law firm. It is a highly scalable business with an organic growth strategy which has a proven record of delivering sustainable growth since its IPO in 2017. Ranked within the UK Top 100 law firms, Keystone provides conventional legal services in a £14bn addressable market through its differentiated platform model which has three defining characteristics:
- Lawyers have freedom, flexibility and autonomy, and are paid up to 75% of what they bill.
- Lawyers determine how, when and where they work, in contrast to the conventional law firm model.
- Lawyers are provided full infrastructure and support via its central office team, bespoke user-friendly IT platform, and network of colleagues and events.
Keystone is a full-service law firm, with extensive experience across a wide range of sectors and specialisms. With over 500 high calibre self-employed Principal lawyers, supported by over 180 other fee earners, Keystone delivers dynamic services to its client base which ranges from fast growing start-ups to multinational corporations and high net worth individuals.
More information about Keystone can be found at www.keystonelaw.co.uk.
Chairman's Statement
It is my pleasure to introduce Keystone Law’s results for the year ended 31 January 2026.
The business has delivered another strong performance, both operationally and financially. A record number of fee earners have joined this year, 61 new principals and 63 pod members, increasing total fee earners by 13.5%. Our lawyers have taken advantage of the sustained, broad based client demand to drive revenue up by 17.9% to £115.2m, producing adjusted PBIT(1) of £12.9m (2025: £11.6m) and adjusted PBT(1) of £15.3m representing a 13.3% margin (2025: £12.7m, 13.0% margin). PBT was £14.7m at a margin of 12.7% (2025: £11.7m, 12.0%), whilst retained earnings were £11.1m (2025: £8.6m). The quality of these earnings is extremely high, as demonstrated by the high level of cash generation at £11.6m pre dividends (2025: £7.2m).
DIVIDEND
The strong level of cash generation from our business model ensures that we are well placed to return value to our stakeholders through our progressive dividend policy in line with which we are proposing to pay a final ordinary dividend of 17.2p. Having paid an ordinary interim dividend of 7.5p (2025: 6.2p), this will bring the total ordinary dividend for the year to 24.7p (2025: 20.2p).
This will bring the total value of dividends paid since IPO to approximately £54m, or equivalent to just over 169p(2) per share, which is 91% of the adjusted earnings(1) generated by the business over the same period.
OUR AI JOURNEY
AI, and the successful application of its technology, has been a significant focus point of the management team this year. We firmly believe that the successful adoption of this new technology will enhance the Keystone proposition for both lawyers and clients. We are focused on identifying and implementing tools and solutions which genuinely improve our service delivery whilst driving user adoption through education and training. We believe that this approach provides further support for our successful growth strategy.
THE KEYSTONE COMMUNITY AT THE HEART OF OUR SUCCESS
Our success is delivered by, and is a reflection of, the people who comprise the Keystone community. Keystone is different by design and this difference extends to the emphasis we place on developing, maintaining and enhancing the Keystone community which sits at the heart of the business. Our community focused business model is a real differentiating factor in attracting and retaining lawyers. By building genuine relationships across the business our approach delivers real value to our clients, as they benefit from multi-lawyer and multi-disciplinary teams which work together with a real understanding and appreciation of both their technical and cultural needs. All of this underpins the long-term sustainable creation of value for all stakeholders.
THE CENTRAL OFFICE TEAM
The hard work and dedication of our central office team delivers a first-class service to our lawyers, and their clients, and is a further differentiating factor on which our success is built. By treating our lawyers as if they were our clients, we ensure an exceptional standard of support. Our focus is always on improving the lawyer and client experience and this is demonstrated consistently through the ongoing investment we make in our people, our systems and our community.
BOARD AND GOVERNANCE
This is the first year that the updated Quoted Companies Alliance (“QCA”) code, which was issued in 2023, became effective in its entirety. We had already adopted a number of the updated guidance included within this ahead of the code timeline and I confirm that this year we have operated within the structures and governance requirements of this updated code throughout the year with the final element needed to satisfy all requirements being the placing of the remuneration report within this annual report before shareholders for a non-binding advisory vote; this will take place at our coming AGM.
OUTLOOK
I am pleased to report that the momentum which we had experienced through 2026 has continued into the early part of 2027 which provides us with confidence for the year ahead.
Robin Williams
Non-executive Chairman
28 April 2026
(1) Adjusted PBT, adjusted PBIT and adjusted earnings are calculated by adding share-based payment costs, gains on assets held at fair value and amortisation of intangible assets to PBT, PBIT or earnings respectively. Details of these calculations are shown in the Financial Review.
(2) Sum of the Ordinary DPS and special dividends DPS paid and proposed for the years ended 31 January 2019 to 31 January 2026.
Chief Executive Officer's Statement
I am delighted to report that the business has continued to trade strongly across the Period, delivering revenue growth of 22.5% and adjusted PBIT(1) growth of 31.6% year on year. We saw strong demand across the business, with activity in corporate and corporate restructuring over-indexing, which has driven revenue per Principal up to £133.8k, an increase of 14.5% on H1 2026. The strength of revenue growth has resulted in an increased adjusted PBIT margin of 12.3% (H1 2026: 11.4%), whilst the effect of interest rates being held has been that we have benefitted from net finance income of £1.5m, producing adjusted PBT(1) of £9.6m at a margin of 14.5% (H1 2026: £6.2m, 13.6%). The highly cash generative nature of our business model continues to underpin the high quality of earnings, with cash generated from operations increasing 19.2% to £8.1m.
The global geo-political uncertainty which has been persistent during the Period has resulted in a softer recruitment market, with candidate movement across the market reduced from the levels experienced during FY2026.
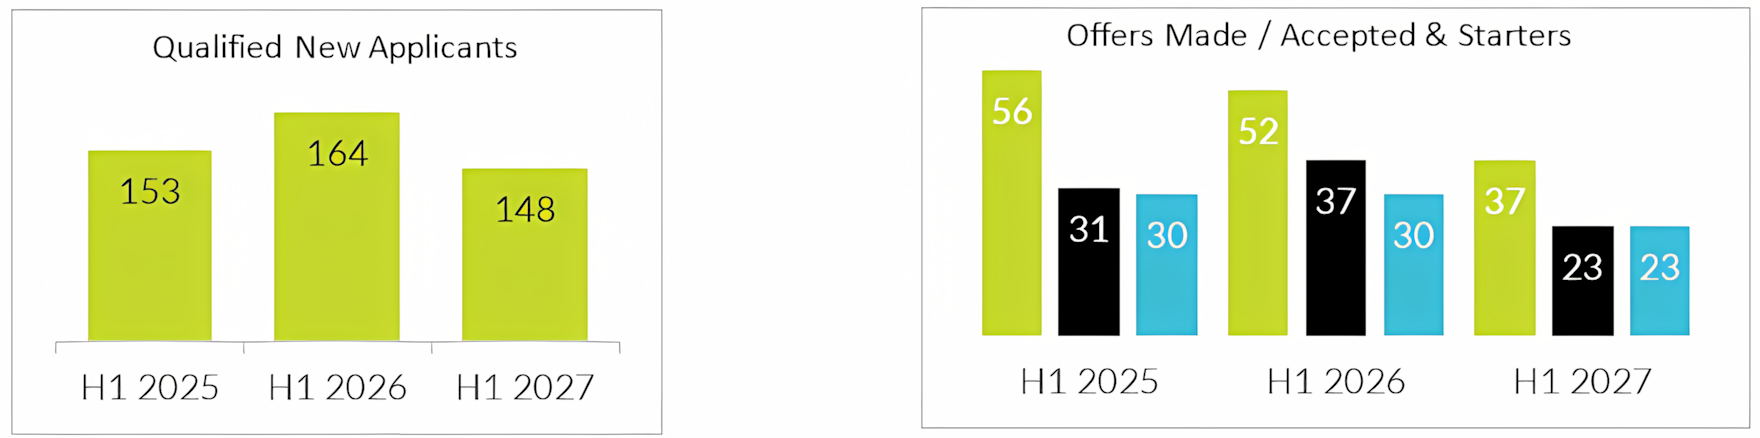
Against this backdrop we delivered a robust performance in attracting talent, adding 23 high calibre new Principals during the Period taking the total number of Principals to 501 (31 January 2026: 491). Furthermore, the strong demand within the business has underpinned the confidence of our lawyers to continue to recruit strongly into their Pods, with 23 new Pod members joining taking the total number of fee earners to 682 (31 January 2026: 654).
As reported in our FY 2026 annual report and accounts, our ongoing implementation and adoption of AI tools and solutions is a natural extension of our established IT strategy, and we continue to embrace the opportunities which this presents for our business. Applying innovative technology solutions which genuinely enhance the user experience of both our lawyers and clients is a part of the Keystone DNA. Having successfully deployed a secure enterprise grade version of ChatGPT and Claude as well as the Netdocuments generative AI tool during FY 2026, we have continued to extend the suite of AI tools available to our lawyers, successfully rolling out CoCounsel Legal (“CoCounsel”) during the Period. As a leading generative AI tool specifically designed to work for the legal industry, CoCounsel’s major differentiating factor is its ability to access not only open-source data but, more importantly, it accesses the extensive, market leading, legal knowledge databases owned by Thomson Reuters. This roll out builds on the successes of last year and we have seen an increasing level of uptake and utilisation of these AI solutions.
We firmly believe that it is only through the active promotion and ongoing training that the business will reap the full benefits of these tailored applications. Accordingly, we continue to invest in supporting both new and existing users to help them leverage the advantages these new solutions provide.
H1 2027 saw the culmination of our brand refresh project with the successful launch of our new website alongside the production of the extensive marketing collateral. This has significantly enhanced the visual perception of our brand, aligning it more accurately with the position which Keystone now occupies in the legal marketplace and amongst our peers.
Outside of these projects, the central office team has continued to drive the business forwards, delivering exceptional support to all aspects of our lawyers’ working lives. We continue to invest in all elements of the business to ensure that we remain the standout choice of those high calibre lawyers we wish to attract and retain. As the market leading Premier platform law firm, “business as usual” for Keystone’s central office team is a process of constant investment and improvement across all aspects of the business, underpinning the delivery of sustainable ongoing long-term success.
I would like to take this opportunity to thank my colleagues, both the lawyers and across the central office team, for their passion and dedication, which continues to drive the business forwards and has made these results possible.
Dividend and Capital Allocation
I am pleased to announce that the Board has declared an interim ordinary dividend of 9.6p per share as well as a special dividend of 15p per share. These dividends will be payable on 16 October 2026 to shareholders on the register on 25 September 2026, and the shares will go ex-dividend on 24 September 2026.
In May, we carried out a £1.5m on-market share buy-back programme. The objective of this programme was to buy sufficient shares to meet the Group’s commitment under the Long Term Incentive Plan this year, thus avoiding any dilution that would otherwise arise through the issue of new shares. Having met these obligations, the small surplus of shares acquired (43,993 shares) were cancelled.
Summary and outlook
We are delighted with these strong results, underpinned by very strong financials, high quality, sustainable growth which continues to drive the business forwards and reinforces our market leading position.
We remain positive about our ongoing success, despite the global geo-political uncertainty which continues to persist.
In light of the successful performance of H1 2027, together with the encouraging start we have had to H2 2027, the Board now expects that Keystone will deliver revenue comfortably ahead and adjusted profits materially ahead of current market expectations(2) for FY 2027.
James Knight
Chief Executive Officer
11 September 2026
(1) Adjusted PBIT and adjusted PBT are calculated using profit before tax and adding back amortisation in the prior period and share-based payments for all periods.
(2) Management understands current market expectations for FY 2027 to be revenue of £123m and adjusted PBIT and adjusted PBT of £13.8m and £15.8m respectively.
FINANCIAL REVIEW AND STRATEGIC REPORT
KEY PERFORMANCE INDICATORS (KPIs)
The following KPIs are used by the management to monitor the financial and operational performance of the Group:
- Revenue growth: 17.9% increase (2025: 11.1%)
- Adjusted PBT(3) growth: 20.6% increase (2025: 12.8%)
- Adjusted PBT margin(3): 13.3% (2025: 13.0%)
- PBT growth: 25.6% increase (2025: 13.4%)
- PBT margin: 12.7% (2025: 12.0%)
- Adjusted basic EPS(3): 37.0p (2025: 30.4p)
- Operating cash conversion: 98.9%(1) (2025: 94.5%)
- Trade receivables days: 35 (2025: 34)
- Qualified new applicants(2): 294 (2025: 283)
- Offers made(2): 96 (2025: 95)
- Offers accepted(2): 68 (2025: 52)
(1) Operating cash conversion is calculated utilising cash generated from operations and dividing it by the PBT before non-cash movements and net interest (2026: £13,621,568 per cash flow statement).
(2) Non-financial KPIs are commented on with the Chief Executive’s review. Recruitment data refers to numbers of potential Principals.
(3) The calculation of adjusted PBT, adjusted PBT margin and adjusted EPS is shown on the next page.
REVENUE
I am delighted to report that revenue increased this year by 17.9% to £115.2m. This strong revenue growth has been driven by broad based client demand and continued strength in recruitment, both of Principals and pod members. In terms of Principal numbers, we ended the period with 491 Principals and averaged 473 (2025: ended with 455 and averaged 443.5), whilst a net increase of 36 pod members means that total fee earners has increased by 13.5% to 654 (2025: 576). These factors have facilitated the continued growth in revenue per Principal, which has increased this year by 10.5% to £243k (2025: £220k).
GROSS PROFIT
The increased revenue this year generated growth in gross profit of 15.2% to £29.3m (2025: £25.5m). The strong revenue growth was driven predominantly by the Principals and their Pods, such that the share of gross profit generated by those lawyers on whom we enjoy enhanced gross margins(4) has fallen. Accordingly, the gross margin of 25.5% was lower than last year (2025: 26.1%), this reduction in margin flows through to PBT.
(4) Enhanced GM% delivered by central office employed lawyers and those lawyers based on the Isle of Man.
DEPRECIATION, AMORTISATION, SHARE-BASED PAYMENTS AND GAINS ON INVESTMENTS
Depreciation has increased this year by £0.1m as the 2024 fit out costs of our Chancery Lane offices only started being depreciated in November 2025. There was no amortisation charge for intangibles this year as the underlying asset on which this had been charged became fully amortised during the prior year (2025: £0.25m). The charge in respect of share-based payments increased from £0.8m to £0.85m, whilst the carrying value of the investment held by the business in Keypoint Law PTY Limited was revalued resulting in an unrealised gain of £0.2m.
OTHER ADMINISTRATIVE EXPENSES
Other administrative expenses have increased by 18.3% to £15.3m (2025: £12.9m). Staff costs increased by 17.0% to £6.3m (2025: £5.4m), driven by the investment in the additional personnel needed (2026: 81, 2025: 69) to ensure that the services provided to our lawyers remain a differentiating factor, together with pay rises and promotions reflective of the competitive market environment.
Other administrative costs (per note 4) increased by 19.3% to £9.0m (2025: £7.5m), most significantly driven by an increased cost in lawyer recruitment fees (up £0.5m year on year) as a number of lawyers with large practices joined this year via recruitment agencies. The other main contributory factors to this increase were the increased investment in IT, costs associated with the brand refresh and the 13.5% increase in the average number of fee earners supported by the business.
FINANCE INCOME AND COSTS
During the first half of this year, we successfully renegotiated with our bank to receive enhanced interest rates on funds held. This, in conjunction with the continued slow pace in the reduction of base rates has meant that we have seen a substantial increase in the net finance income received (2026: £2.4m, 2025: £1.1m).
PBT, ADJUSTED PBT AND PBT MARGINS
Adjusted PBT is calculated as follows:
|
2026
£ |
2025
£ |
Profit before tax |
14,671,612 |
11,684,999 |
Gain in respect of investment held at fair value |
(184,388) |
– |
Amortisation of intangible assets |
– |
248,543 |
Share-based payments |
851,320 |
780,662 |
Adjusted PBT |
15,338,544 |
12,714,204 |
Net finance income |
2,408,050 |
1,111,203 |
Adjusted PBIT |
12,930,474 |
11,603,001 |
|
|
|
PBT margin |
12.7% |
12.0% |
Adjusted PBIT margin |
11.2% |
11.9% |
Adjusted PBT margin |
13.3% |
13.0% |
The Board consider adjusted PBT and adjusted PBIT to be better measures of performance than PBT or PBIT, as the adjustments made exclude items which are either not a result of the underlying performance of the business (as is the case for the unrealised gain on the investment held at fair value or the amortisation, in the prior years, which arose from the structuring of the 2014 private equity investment in the business) or where the cost represents neither a cash impact to the business, nor is it a reflection of the value received by the recipient (as is the case with share-based payment costs).
The decline in the adjusted PBIT [margin] is predominantly the result of the lower gross margin, with the full year impact of depreciation of the office fit out causing much of the remainder.
TAXATION
The Group’s effective rate of corporation tax this year was 24.6% (2025: 26.8%). The reason that this is below the standard rate of corporation tax, and indeed the normal rate for the Group, is that at 31 January 2025 we prudently did not assume that the costs of the fit out of our offices in Chancery Lane would qualify for the annual investment allowance and as such enjoy 100% deduction in the year. During the subsequent tax work it was concluded that they did qualify, thereby reducing the charge to tax in the year. Excluding the benefit of this one-off transaction, the underlying corporation tax would have been 26%; higher than the standard rate and reflective of the level of investment which the Group makes in providing networking opportunities for our lawyers in social environments which are disallowable for corporation tax purposes.
EARNINGS PER SHARE
Basic earnings per share increased from 27.1p to 34.9p, with fully diluted EPS being 34.3p (2025: 26.6p). Adjusted basic earnings per share (calculated by making the same adjustments to earnings as have been made in calculating adjusted PBT and divided by the average shares in issue this year) increased to 37.0p (2025: 30.4p).
STATEMENT OF FINANCIAL POSITION
CASH
One of the key features of the Group’s business model is its strong cash generation. Keystone is a capital light model where the largest element of its costs, the payment of its lawyers, is on a pay when paid basis. These characteristics are clearly demonstrated in the Group’s cashflow statement. Operating cash conversion of 98.9% (2025: 94.5%) generating cash from operations of £13.5m (2025: £11.5m), and capital expenditure returned to its usual levels of £0.1m following the one-off increase in 2025 to reflect the fit out of the offices in Chancery Lane.
Corporation tax paid this year (£3.7m) also reflects a return to “normal” insofar as it includes four quarterly payments. This follows the distortion to cashflow caused in 2025 as the business transitioned to meet the requirements of being classified as “super large” by HMRC. This classification means that the business has to pay 100% of the corporation tax due within the financial year and so 2025 was a transitional year in which 6 quarterly payments were made.
The newly renegotiated interest rates on cash held have ensured a step up in interest received this year (£3.2m, 2025: £2.0m) whilst interest paid remained largely in line with the prior year.
Overall, these movements have meant that the Group generated £11.6m (2025: £7.2m) pre dividend payments. This strong cash generation, together with the broader strength of the balance sheet underpinned the Group’s ability to pay dividends in the year of £11.6m, comprising £4.7m in respect of a special dividend and £6.8m in respect of ordinary dividends (2025: £5.9m ordinary dividends). This left closing cash of £9.7m (2025: £9.7m).
NET ASSETS
The strength of performance of the Group continues to ensure that we have an extremely strong balance sheet. Even after a year where we have paid out £11.6m in dividends, net assets have increased from £20.4m to £20.7m. This has been driven by strong profitability (£11.1m) and the £0.7m movement in reserves to account for the vesting of LTIP awards.
SECTION 172 COMPANIES ACT STATEMENT
The statements below address the reporting requirements of the Board under Section 172 of the Companies Act and the Companies (Miscellaneous Reporting) Regulations 2018.
The Directors of the Company have a duty to promote the success of the Company. A Director of the Company must act in the way they consider, in good faith, to promote the success of the Company for the benefit of its members, and in doing so have regard (amongst other matters) to:
• the likely consequences of any decision in the long term;
• the interests of the Company’s employees;
• the need to foster the Company’s operations on the community and the environment;
• the desirability of the Company to maintain a reputation for high standards of business conduct; and
• the need to act fairly between members and the Company.
The Directors are committed to developing and maintaining a governance framework that is appropriate to the business and supports effective decision making coupled with robust oversight of risks and internal controls.
Keystone has a very clear organic growth strategy aimed to ensure delivery of long-term sustainable growth and increasing stakeholder value and all significant business decisions consider both their short and long-term impact on this strategy. Fundamental to the success of this strategy is the continued recruitment and retention of high-calibre lawyers, who join Keystone to take advantage of the many benefits that we offer and build their practice to deliver work of the highest professional standards to our clients. A key tenet of our success is the ongoing investment we make in nurturing the community and culture of the business. This open, engaging and collegiate culture both attracts and retains lawyers whilst ensuring that all who work at Keystone feel a part of something special.
Keystone’s primary asset is its people, be it the central office staff, the lawyers, the clients or third-party suppliers with whom we work (such as counsel, experts and other professionals). As a business, we dedicate substantial time, effort and resources in working to develop and maintain strong relationships from which all parties benefit. As a people business, the impact of business decisions on our principal stakeholders is always central to the decision-making process.
Law firms generally have a low environmental impact and Keystone’s model further reduces this by having an extremely small office footprint and using technology across the business to facilitate our lawyers working remotely and so having no need to commute to work.
The Directors treat all members of the Group fairly and consistently, as required by both professional standards and in compliance with various pieces of legislation. We provide information to all shareholders and other third parties on an equal basis.
Below are some examples of how the Directors have had regard to the matters set out in section 172 in decisions made when discharging their duties:
Approval of annual budget
The Board has reviewed its plans for the coming year, considering the financial and operational implications these have. These plans continue to focus on driving the continued growth of the lawyer base whilst ensuring that, through the delivery of market leading support services, we facilitate the growth and development of those lawyers who are already with the Group. This approach is intended to deliver long-term sustainable growth which is beneficial to all stakeholders.
DIVIDEND
Reflective of the strong cash generation of the business model, recognising the strength of our balance sheet and our confidence in the future, the Board is proposing to pay a final ordinary dividend for the year ended 31 January 2026 of 17.2p per share (2025: 14.0p). This brings the total ordinary dividend for the year to 24.7p per share (2025: 20.2p per share). Subject to approval at the Annual General Meeting, the final dividend will be paid on 23 June 2026 to shareholders on the register at the close of business on 5 June 2026.
The cash value of dividends paid this year was £11.6m, comprising £4.7m in respect of a special dividend and £6.8m in respect of ordinary dividends (2025: £5.9m ordinary dividends).
Ashley Miller
Finance Director
28 April 2026
CONSOLIDATED STATEMENT OF COMPREHENSIVE INCOME
For the period ended 31 July 2026
| |
Note |
6 months to July
2026
(Unaudited)
£ |
6 months to July
2025
(Unaudited)
£ |
| Revenue |
|
66,348,606 |
54,151,537 |
| Cost of sales |
|
(49,435,074) |
(40,358,020) |
| Gross profit |
|
16,913,532 |
13,793,517 |
| Trade receivables impairment |
|
(1,108,171) |
(265,266) |
| Corresponding reduction in trade payables |
|
809,814 |
180,059 |
|
|
(298,357) |
(85,207) |
| Administrative expenses |
2 |
(8,265,070) |
(7,211,696) |
| Depreciation |
2 |
(346,214) |
(346,456) |
| Share-based payments |
2 |
(392,136) |
(408,852) |
| Other operating income |
|
145,562 |
43,461 |
| Operating profit |
|
7,757,317 |
5,784,767 |
| Finance income |
|
1,766,223 |
1,578,727 |
| Finance costs |
|
(280,213) |
(431,834) |
| Profit before tax |
|
9,243,327 |
6,931,660 |
| Corporation tax expense |
|
(2,326,443) |
(1,724,898) |
| Profit and total comprehensive income for the period attributable to equity holders of the Parent |
|
6,916,884 |
5,206,762 |
| Basic EPS (p) |
1 |
21.8 |
16.5 |
| Diluted EPS (p) |
1 |
21.4 |
16.2 |
|
|
|
|
The above results were derived from continuing operations.
CONSOLIDATED STATEMENT OF FINANCIAL POSITION
As at 31 July 2026
| |
Note |
31 July 2026
(Unaudited)
£ |
31 July 2025
(Unaudited)
£ |
31 January 2026
(Audited)
£ |
| Assets |
|
|
|
|
| Non-current assets |
|
|
|
|
| Property, plant and equipment |
|
|
|
|
| – Owned assets |
|
553,645 |
690,053 |
629,880 |
| – Right-of-use assets |
|
1,278,058 |
1,741,680 |
1,509,869 |
| Total property, plant and equipment |
|
1,831,703 |
2,431,733 |
2,139,749 |
| Intangible assets |
|
4,807,411 |
4,807,411 |
4,807,411 |
| Investments |
|
313,738 |
129,350 |
313,738 |
| |
|
6,952,852 |
7,368,494 |
7,260,898 |
| Current assets |
|
|
|
|
| Trade and other receivables |
3 |
37,905,294 |
30,043,484 |
32,787,578 |
| Corporation tax |
|
– |
– |
37,179 |
| Cash and cash equivalents |
|
10,462,544 |
6,505,516 |
9,744,084 |
| |
|
48,367,838 |
36,549,000 |
42,568,841 |
| Total assets |
|
55,320,690 |
43,917,494 |
49,829,739 |
| Equity and liabilities |
|
|
|
|
| Equity |
|
|
|
|
| Share capital |
|
63,346 |
63,435 |
63,435 |
| Share premium |
|
9,920,760 |
9,920,760 |
9,920,760 |
| Share-based payments reserve |
|
607,086 |
968,590 |
1,411,055 |
| Retained earnings |
|
10,485,676 |
5,827,556 |
9,301,975 |
| Equity attributable to equity holders of the Parent |
|
21,076,868 |
16,780,340 |
20,697,225 |
| Non-current liabilities |
|
|
|
|
| Lease liabilities |
|
819,194 |
1,320,595 |
1,072,496 |
| Provisions |
|
1,227,354 |
1,198,130 |
1,340,830 |
| |
|
2,046,548 |
2,518,725 |
2,413,326 |
| Current liabilities |
|
|
|
|
| Trade and other payables |
|
30,983,653 |
23,942,119 |
26,124,340 |
| Lease liabilities |
|
594,848 |
594,848 |
594,848 |
| Corporation tax liability |
|
618,773 |
81,462 |
– |
| |
|
32,197,274 |
24,618,429 |
26,719,188 |
| Total liabilities |
|
34,243,821 |
27,137,154 |
29,132,514 |
| Total equity and liabilities |
|
55,320,690 |
43,917,494 |
49,829,739 |
The interim statements were approved and authorised for issue by the Board of Directors on 11 September 2026 and were signed on its behalf by:
A Miller
Director
CONSOLIDATED STATEMENT OF CHANGES IN EQUITY
For the period ended 31 July 2026
|
Attributable to equity holders of the Parent |
Share capital
£ |
Share premium
£ |
Share-based
payment
reserve
£ |
Retained
earnings
£ |
Total
£ |
| At 31 January 2025 (audited) |
63,186 |
9,920,760 |
1,276,080 |
9,102,454 |
20,362,480 |
| Profit for the period and total comprehensive income |
– |
– |
– |
5,206,762 |
5,206,762 |
| Transactions with owners |
|
|
|
|
|
| Share-based payments vesting |
249 |
– |
(716,345) |
716,345 |
249 |
| Share-based payments awards |
– |
– |
408,852 |
– |
408,852 |
| Dividends paid |
– |
– |
– |
(9,198,002) |
(9,198,002) |
| At 31 July 2025 (unaudited) |
63,435 |
9,920,760 |
968,590 |
5,827,556 |
16,780,340 |
| Profit for the period and total comprehensive income |
– |
– |
– |
5,853,214 |
5,853,214 |
| Transactions with owners |
|
|
|
|
|
| Share-based payments vesting |
– |
– |
– |
– |
– |
| Share-based payments awards |
– |
– |
442,468 |
– |
442,468 |
| Dividends paid |
– |
– |
– |
(2,378,798) |
(2,378,798) |
| At 31 January 2026 (audited) |
63,435 |
9,920,760 |
1,411,055 |
9,301,975 |
20,697,225 |
| Profit for the period and total comprehensive income |
– |
– |
– |
6,916,884 |
6,916,884 |
| Transactions with owners |
|
|
|
|
|
| Share-based payments vesting |
– |
– |
(1,196,105) |
1,196,105 |
– |
| Share-based payments awards |
– |
– |
392,136 |
– |
392,136 |
| Purchase of own shares into treasury |
– |
– |
– |
(1,510,556) |
(1,510,556) |
| Cancellation of shares |
(89) |
– |
– |
– |
(89) |
| Dividends paid |
– |
– |
– |
(5,418,732) |
(5,418,732) |
| At 31 July 2026 (unaudited) |
63,346 |
9,920,760 |
607,086 |
10,485,676 |
21,076,868 |
CONSOLIDATED STATEMENT OF CASH FLOWS
For the period ended 31 July 2026
| |
Note |
6 months to July
2026
(Unaudited)
£ |
6 months to July
2025
(Unaudited)
£ |
Year ended 31 January
2026
(Audited)
£ |
| Cash flows from operating activities |
|
|
|
| Profit before tax |
|
9,243,327 |
6,931,660 |
14,671,612 |
| Adjustments to cash flows from non-cash items |
|
|
|
| Depreciation |
2 |
346,214 |
346,056 |
691,074 |
| Share-based payments |
|
392,136 |
408,852 |
851,320 |
| Revaluation of investment |
|
– |
– |
(184,388) |
| Finance income |
|
(1,766,223) |
(1,578,727) |
(3,196,726) |
| Finance costs |
|
280,213 |
431,834 |
788,676 |
|
|
8,495,667 |
6,539,675 |
13,621,568 |
| Working capital adjustments |
|
|
|
|
| (Increase) in trade and other receivables |
(5,117,716) |
(1,717,939) |
(4,462,033) |
| Increase in trade and other payables |
4,859,838 |
1,956,881 |
4,139,102 |
| (Decrease) / Increase in provisions |
|
(113,475) |
35,895 |
178,595 |
| Cash generated from operations |
|
8,123,789 |
6,814,512 |
13,477,232 |
| Interest paid on client balances |
|
(236,092) |
(377,191) |
(684,708) |
| Interest portion of lease liability |
|
(44,121) |
(54,643) |
(103,968) |
| Corporation taxes paid |
|
(1,670,492) |
(1,670,492) |
(3,675,873) |
| Cash generated from operating activities |
6,173,084 |
4,712,186 |
9,012,683 |
| Cash flows from/(used in) investing activities |
|
|
|
| Interest received |
|
1,766,223 |
1,578,727 |
3,196,726 |
| Purchases of property, plant and equipment |
(38,170) |
(32,432) |
(85,068) |
| Net cash generated from/(used in) investing activities |
1,728,053 |
1,546,295 |
3,111,658 |
| Cash flows from financing activities |
|
|
|
|
| Proceeds from issue of ordinary shares |
|
– |
248 |
249 |
| Proceeds from LTIP vesting shares issued from treasury |
|
448 |
– |
– |
| Purchase of own shares into treasury |
|
(1,510,566) |
– |
– |
| Lease repayments |
|
(253,827) |
(251,383) |
(490,878) |
| Dividends paid |
|
(5,418,732) |
(9,189,002) |
(11,576,800) |
| Net cash (used in) financing activities |
(7,182,677) |
(9,440,137) |
(12,067,429) |
| Net (decrease)/increase in cash and cash equivalents |
|
718,460 |
(3,181,656) |
56,912 |
| Cash at 1 February |
|
9,744,084 |
9,687,172 |
9,687,172 |
| Cash at 31 July |
|
10,462,544 |
6,505,516 |
9,744,084 |